A deferred sale of home order, which California lawyers usually call a Duke order, temporarily delays the sale of the family home and gives one parent exclusive use and possession of it after a divorce.[1] It exists to reduce the harm a move would do to a minor child. Before a judge grants one, the parent asking for it has to clear a money gate: the court must find it economically feasible to keep up the payments on the home throughout the deferral.[2] Only then does the judge reach the child's side of it, weighing ten separate factors that run from the child's grade in school to the economic detriment suffered by the parent who leaves.[3]
- What a deferred sale of home order actually does
- First the money question: can the house carry itself?
- The ten factors a judge weighs
- What the delay costs the parent who moves out
- The tax rule that protects a $250,000 exclusion
- Where deferrals go wrong in Orange County
- Five things to settle before you agree to one
- Frequently asked questions
- Sources and disclosures
Most divorcing couples in Orange County start from the same place. Sell the house, split the equity, move on. For plenty of families that is the right answer and the fastest route to two stable households.
Then somebody says the word kids. One parent has a junior at University High in Irvine who is eighteen months from graduating, and the thought of moving her across the district in the middle of it stops the conversation cold. That is usually the moment people start searching for whether a court can simply postpone the sale. In California it can, and the mechanism has a name.
What a deferred sale of home order actually does
California law calls it a deferred sale of home order. Lawyers call it a Duke order.
The statute defines it as an order that temporarily delays the sale of the family home and awards the temporary exclusive use and possession of the family home to a custodial parent of a minor child, whether or not that parent has sole or joint custody, in order to minimize the adverse impact of the dissolution of marriage on the welfare of the child.[1]
Two words in that definition do most of the work. Temporarily. And child.
A deferral is not a property award. Nobody is handing the house to the parent who stays. The community interest survives untouched and the equity is still divided on paper. The sale simply happens on a later date. The statute even gives the parent who requested the order its own label, resident parent, which is how you will see it written in your judgment.[1]
The child requirement is not a formality either. This chapter sits inside the support division of the Family Code and it is built around a minor child, or a child for whom support is authorized.[1] No qualifying child, no Duke order. Couples without minor children who want to delay a sale are negotiating a private agreement between themselves, not asking a court for a statutory remedy, and that difference becomes very important the day one of them changes their mind.
First the money question: can the house carry itself?
Before a judge looks at schools or bedrooms, there is a gate. Most requests that fail die right here, and it has nothing to do with the children.
Family Code section 3801 requires the court to determine whether it is economically feasible to maintain the payments on any note secured by a deed of trust against the home, the property taxes, and the insurance for the home during the deferral period.[2] The court also asks whether the house can be kept in substantially the same condition it was in at the time of trial.
The money to do that can come from the resident parent's own income, from spousal support, from child support, or from any other source of funds the court can identify.[2]
The Legislature was unusually direct about why the gate exists. It is there to avoid the risk of loan default and foreclosure, inadequate insurance coverage, deterioration of the condition of the family home, and other circumstances that would jeopardize both parents' equity in the home.[2]
Read that last clause again. Both parents' equity. The feasibility test was not written to protect the parent who stays. It is there to stop a deferral from quietly destroying an asset that still belongs to two people.
In practice this is arithmetic, and sympathy does not move it. A Mission Viejo house with a payment the resident parent cannot cover on their own does not become affordable because a judge feels for a seventh grader. If documented income plus support cannot carry the loan and the tax bill with enough margin left to replace a failed water heater, the request is over before anyone opens a school calendar.
The ten factors a judge weighs
Clear the money gate and the analysis opens up. Section 3802 sets out what the court considers in deciding whether to grant or deny a deferral, and the list is longer than most people expect.[3]
| What section 3802 lists | What it looks like in a real Orange County case |
|---|---|
| The length of time the child has resided in the home | A child who moved in last year is a far weaker case than one who has never lived anywhere else. |
| The child's placement or grade in school | A high school senior is an easier ask than a second grader, because the deferral being requested is shorter. |
| Accessibility and convenience of the home to the child's school and other services | In Irvine this often decides the whole question. School assignment follows the address, so a move of two miles can mean a different campus. |
| Whether the home has been adapted for a physical disability | If the house was modified for the child or for the resident parent, a move can undo care arrangements that took years to build. |
| The emotional detriment to the child associated with a change in residence | The factor everyone leads with, and the hardest one to evidence without a professional involved. |
| Whether the location lets the resident parent continue working | A parent whose job depends on staying twenty minutes from the house has a concrete argument here rather than a sentimental one. |
| Each parent's financial ability to obtain suitable housing | Cuts both ways. If the departing parent cannot house the child on their half of the equity, the court notices that too. |
| The tax consequences to the parents | Rarely argued well, and usually left on the table. See the residence requirement below. |
| The economic detriment to the nonresident parent | The counterweight. Your ex is invited by statute to put a number on what waiting costs them. |
| Any other factors the court deems just and equitable | The catch-all, and where a party who has behaved badly tends to lose ground. |
Factor nine is the one people forget they are up against. The parent who moves out is not merely inconvenienced in the eyes of the court. They hold a recognised economic interest in the sale happening sooner, and the statute invites them to quantify it.
What the delay costs the parent who moves out
Here is the part that rarely gets said out loud in a first meeting.
A deferral converts half of someone's net worth into an illiquid position in one Orange County house, for a period they do not control, while they try to buy a replacement home in that same market. If prices rise, they have made money on paper that they cannot touch and cannot manage. If prices fall, they absorb half of the fall without ever having been given the option to sell.
They are usually also trying to qualify for a new mortgage while their name still sits on the old one. Lenders see that loan. Whether it counts against them depends on how the judgment is written and on what that lender's guidelines say in a given year, which is a conversation to have with a loan officer before the order is signed rather than after.
None of this makes a deferral wrong. It makes it expensive, and the bill is paid by one specific person. Pretending otherwise is how these arrangements fall apart in year two.
A deferral does not make the house cheaper. It moves the cost onto the parent who leaves, and that bill comes due quietly.
Paula Aragone, Aragone & Associates
Weighing a deferral against a buyout?
We sit in the middle of these conversations as a neutral party and give each side the same numbers at the same moment.
Schedule a Free ConsultationThe tax rule that protects a $250,000 exclusion
This is the most valuable thing in this article, and it fits in one sentence of a judgment.
When a married couple sells a principal residence together, they can exclude up to $500,000 of gain. Filing single or married filing separately, the figure is $250,000 each.[4] To claim it you generally have to have used the home as your main home for a qualifying period. The parent who moves out in year one of a long deferral has an obvious problem with that requirement.
The IRS addresses it head on. Under its rules for separated or divorced taxpayers, you can treat the home as your residence if you are a sole or joint owner and your spouse or former spouse is allowed to live in the home under a divorce or separation instrument and uses it as his or her main home.[4]
That clause does the work. If the judgment says the resident parent occupies the home under the terms of the order, the departing parent's residence requirement keeps running while they are living somewhere else entirely.
Leave it out and a deferral that runs four years can push the departing spouse past the residence requirement and cost up to $250,000 of excluded gain, on a Corona del Mar or Newport Coast property where the gain genuinely is that large. I have watched that language get added in five minutes at a settlement conference because somebody thought to ask. I have also read judgments that never mention it at all.
We are real estate professionals rather than tax advisors, so the arithmetic for your return belongs to your CPA. Ask them about this provision by name before the judgment is signed, not in April.
Ask for it in writing. The protective language is simply a description of who may occupy the home under the order. If your marital settlement agreement does not state that the resident parent lives in the property under the terms of the deferral, ask your attorney whether it should, and have your CPA confirm what it does for your return.
Where deferrals go wrong in Orange County
I will take a position here, because clients ask and "it depends" is not an answer on its own.
For a high-equity house, a deferral is usually the wrong tool. In Corona del Mar or on the Newport Coast, where a long-held property can carry seven figures of gain and a payment to match, you are asking one party to leave several million dollars parked in an asset they cannot touch and cannot manage, for years. The carrying cost is high enough that the feasibility test is difficult to pass honestly, and the gain is often large enough that two exclusions will not absorb it anyway. In those cases the better structure is usually a sale with a carefully chosen closing date, or a buyout priced properly from the start. I have also written about what happens when one spouse refuses a buyout, which is the usual next question.
For a modest-equity house with a short runway, a deferral is often exactly right. A Lake Forest or Mission Viejo home, a child two years from graduating, a payment one parent can comfortably carry, and equity that neither party needs immediately: that is the case the statute was written for, and it works.
The variable that matters most is not the dollar amount. It is the runway.
A deferral with a defined, short, non-negotiable end date tends to hold. One that runs eight years behind a vague trigger tends to end in a motion. I have seen it work both ways, including one deferral that ran nearly a decade without a single dispute because both parties were unusually disciplined about what they had written down. That is not the common case, and I would not plan around it.
Five things to settle before you agree to one
If you are heading toward a deferral, settle these before the order is signed. Every one of them is cheap now and expensive later.
- Get a real net sheet for selling today. Not a website estimate. Actual proceeds after commission, title, county transfer tax and the payoff demand from your lender, so both parties are arguing from the same number instead of from two different guesses.
- Get a second net sheet for the deferral end date, run on a conservative appreciation assumption and an updated loan balance. If the two sheets land close together, the deferral is cheaper than it looks. If they are far apart, somebody is carrying a risk nobody has priced.
- Fix the end date and name what ends it early. Section 3807 lets the court modify or terminate the order at any time at its discretion unless the parties agreed otherwise in writing, so your written terms are what give the arrangement any stability at all.[5]
- Allocate maintenance and capital improvements explicitly. Section 3806 lets the court specify each party's respective responsibility for routine maintenance and for capital improvement costs.[6] A roof is a capital improvement. Decide now who writes that check.
- Get the residence language into the judgment, have your CPA review it, then name who selects the listing agent when the deferral ends. Choosing that person while everyone is still cooperating avoids a stalemate at the exact moment the house needs to go on the market.
Before the hearing, you should be able to answer all of these without looking anything up:
- Can the resident parent carry the home on documented income plus support?
- What is the end date, in writing, and what ends it sooner?
- Who pays for a failed air conditioner, and who pays for a new roof?
- Does the judgment describe the resident parent's occupancy under the order?
- Has a loan officer confirmed how the existing mortgage affects the departing parent's next purchase?
Frequently asked questions
What is a deferred sale of home order in California?
It is a court order that temporarily delays the sale of the family home and gives one parent exclusive use and possession of it, so a minor child is not forced to move during a divorce. California Family Code section 3800 defines it, and lawyers often call it a Duke order. The home is still community property and the equity is still divided. Only the timing of the sale changes.
How long can a deferred sale of home order last?
There is no fixed maximum in the statute. Most orders run until a defined event, usually the youngest child finishing high school. Family Code section 3807 says that unless the parties agreed otherwise in writing, the court may modify or terminate the order at any time at its discretion, so a deferral is never truly locked in.
Can my ex force the sale of the house during a deferral?
Not unilaterally, but the order is not permanent either. Either parent can ask the court to modify or terminate it, and the judge has discretion to grant that. A material change, such as the resident parent no longer being able to afford the payments, is the usual reason a deferral ends early.
Who pays the mortgage and repairs during a deferred sale of home order?
Whatever the order says. Family Code section 3806 lets the court specify each party's responsibility for routine maintenance and capital improvement costs. If your judgment is silent on repairs, you will argue about the roof later, so this belongs in writing before the order is signed.
Does deferring the sale cost me my capital gains exclusion?
It does not have to. IRS Publication 523 says a sole or joint owner can treat the home as a main residence if the ex-spouse is allowed to live there under a divorce or separation instrument and uses it as a main home. Get that language into the judgment. Without it, a long deferral can push the departing spouse past the residence requirement and cost up to $250,000 of excluded gain.
Sources and disclosures
- California Family Code section 3800, definitions of deferred sale of home order, custodial parent and resident parent. codes.findlaw.com/ca/family-code/fam-sect-3800
- California Family Code section 3801, economic feasibility and the Legislature's stated purpose. codes.findlaw.com/ca/family-code/fam-sect-3801
- California Family Code section 3802, factors the court considers in granting or denying a deferred sale of home order. codes.findlaw.com/ca/family-code/fam-sect-3802
- Internal Revenue Service, Publication 523, Selling Your Home, sections on maximum exclusion and on separated or divorced taxpayers. irs.gov/publications/p523
- California Family Code section 3807, modification or termination of a deferred sale of home order. codes.findlaw.com/ca/family-code/fam-sect-3807
- California Family Code section 3806, responsibility for routine maintenance and capital improvement costs. codes.findlaw.com/ca/family-code/fam-sect-3806
Statutory text reviewed on November 9, 2026. California statutes are amended regularly, so confirm the current language with your attorney before relying on any section cited here. This article describes how these orders affect a real estate decision and is general information rather than legal or tax advice.
Stay connected
New guides on Orange County real estate every week. Subscribe to the blog, listen to the podcast on Spotify, or follow along on Instagram and YouTube.
Paula Aragone
Aragone & Associates
Call or text 949-415-4784
Email [email protected]
We are real estate professionals and not real estate attorneys, accountants or tax advisors. Nothing here is legal, tax or financial advice. Please consult your own attorney and CPA about your specific circumstances before signing a judgment or listing a property.
Paula Aragone, CA DRE #01364746
Aragone & Associates | First Team Real Estate, CA DRE #01008773
4 Corporate Plaza Suite 100, Newport Beach, CA 92660
Tags: deferred sale of home order, Duke order, divorce real estate, Orange County divorce, selling a house in divorce, California Family Code, capital gains exclusion, Newport Beach
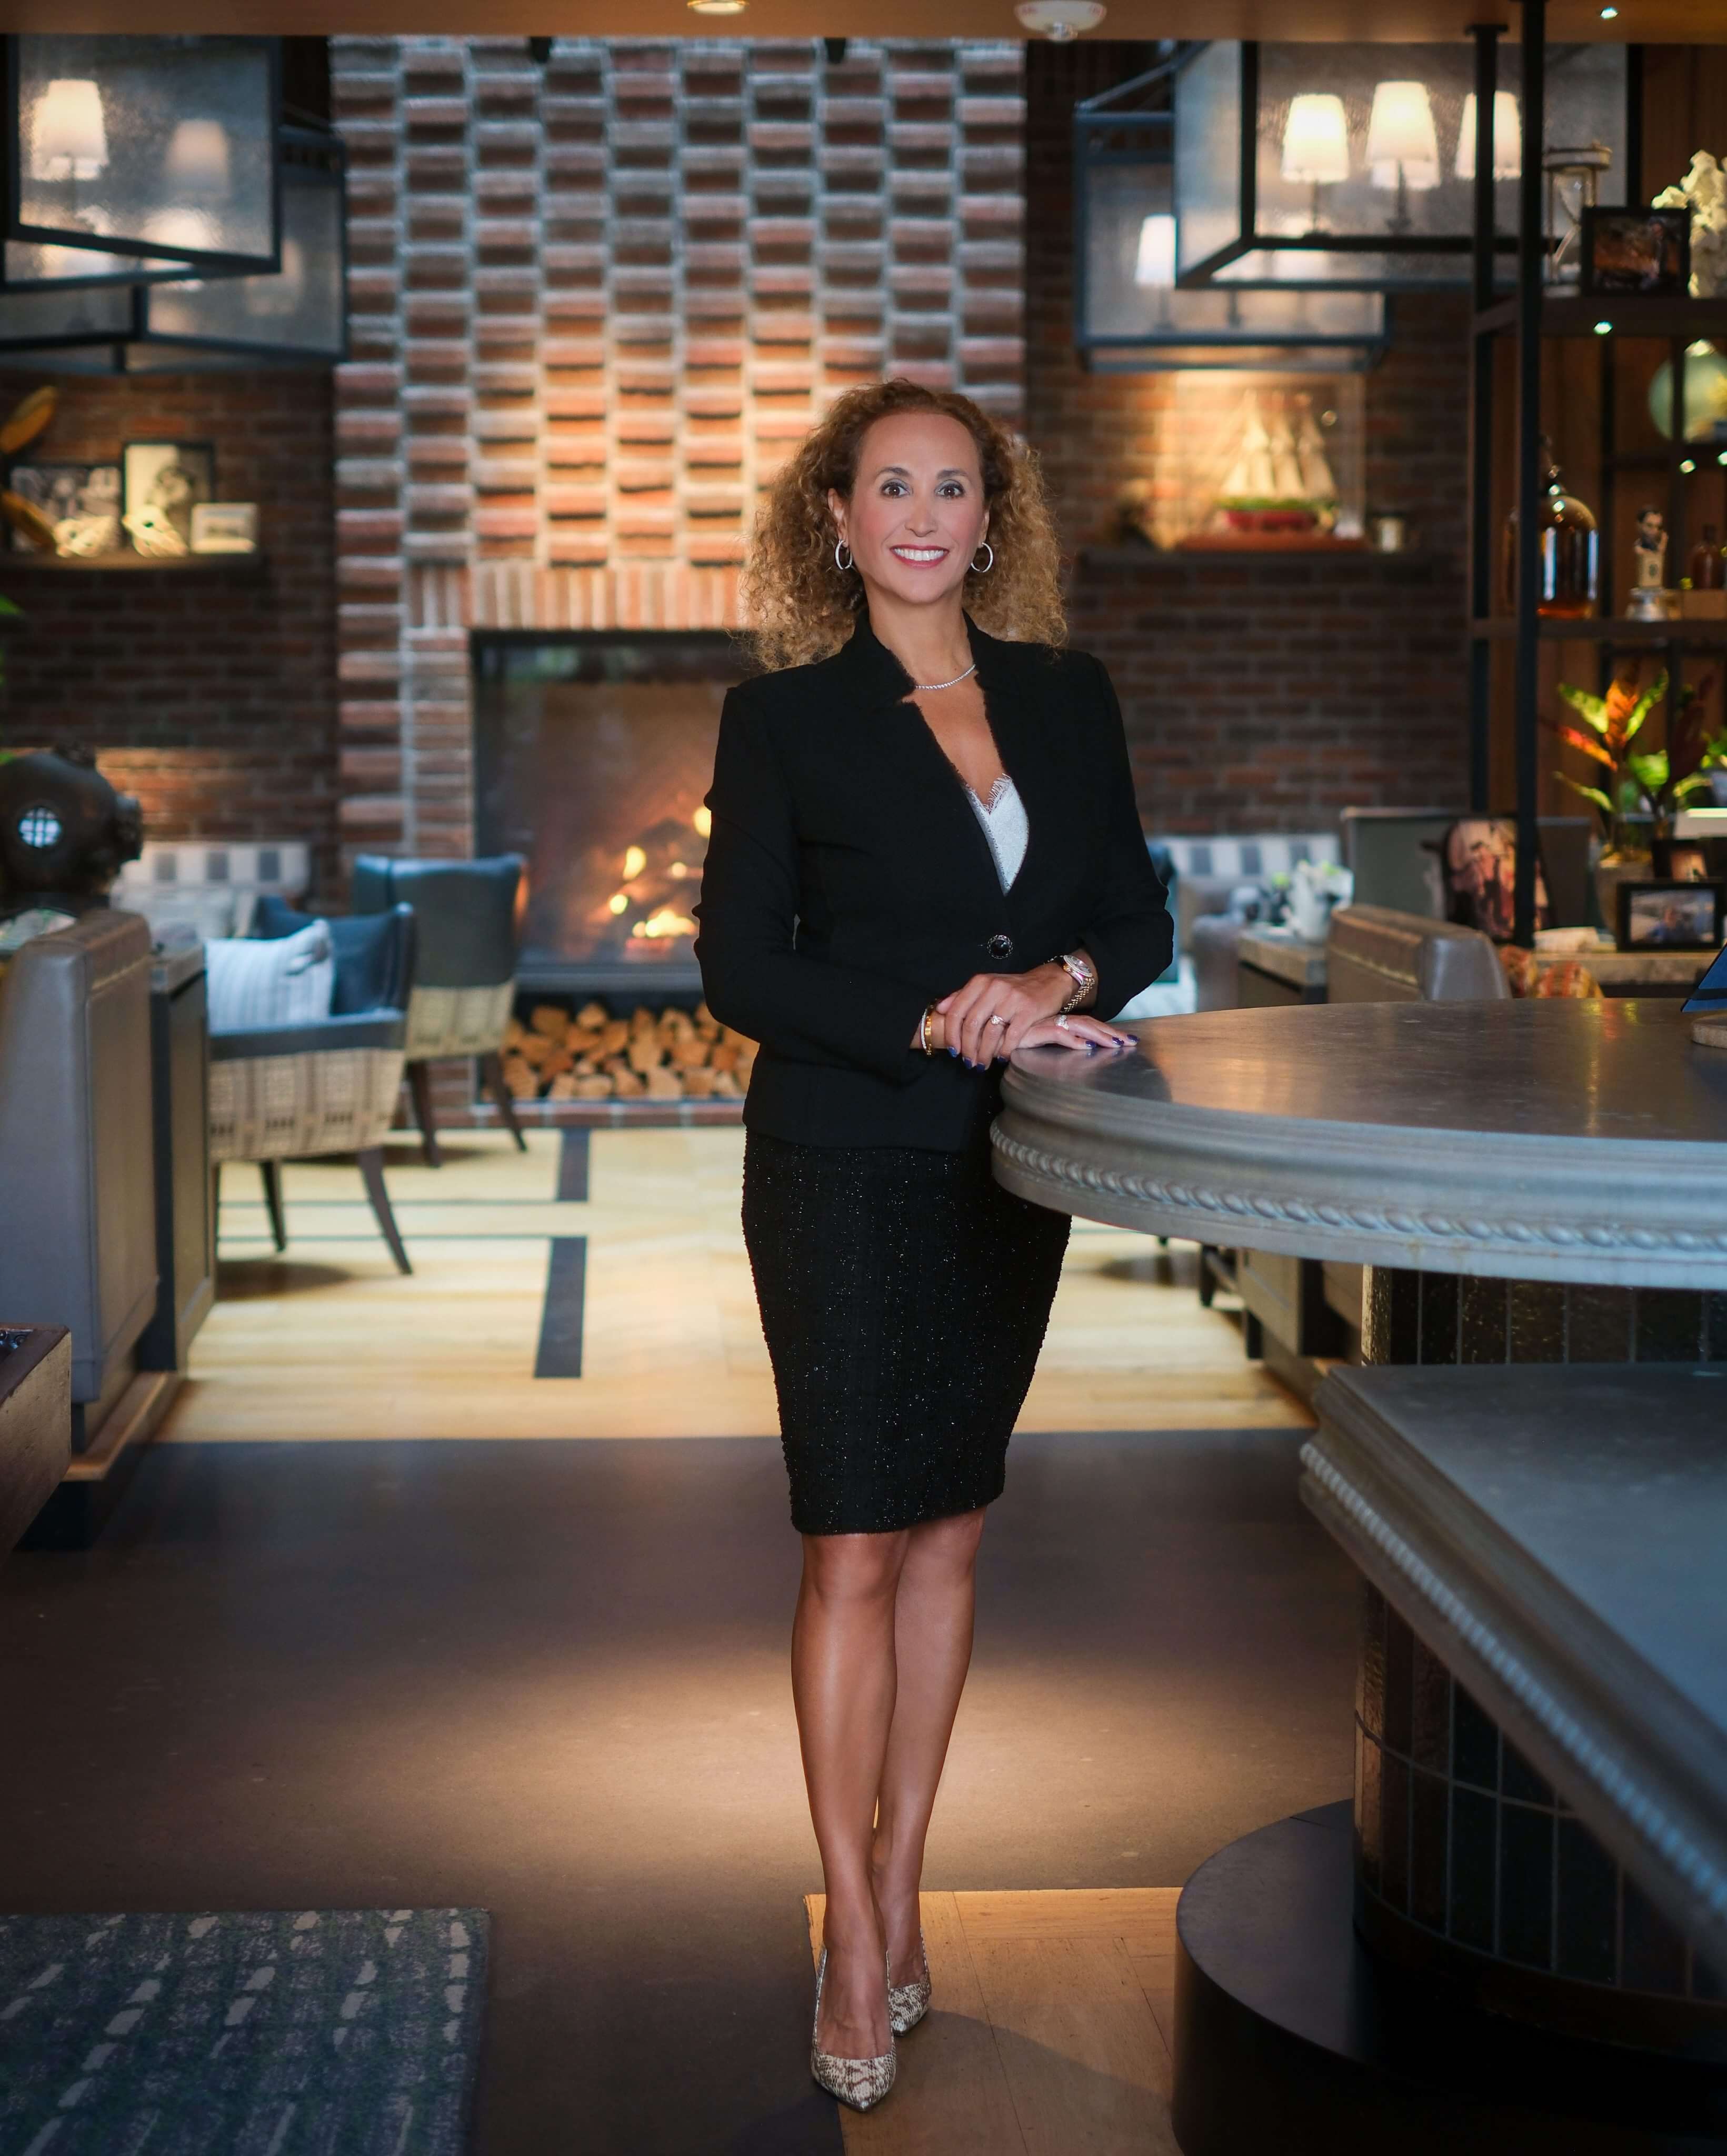
Paula Aragone has spent more than 23 years in Orange County real estate, with over 900 transactions and more than $900 million in sales. She works divorce, probate and trust sales as a neutral third party, which means both sides get the same numbers at the same time, and she brings a law school background to transactions where the paperwork decides the outcome.
Talk it through before you sign anything.
A short conversation now is cheaper than a motion in two years. We will run both sets of numbers and tell you honestly which way we would go.
Call (949) 415-4784Schedule a Consultation