The short answer
You are not required to accept a buyout. An offer from your spouse is an offer, and that is all it is. You can decline it, counter it, or ask the court to order the house sold instead.
People sign these agreements every week believing the offer on the table was the only option available to them. By the time they find out otherwise, the judgment is entered and the room to negotiate is gone. Understanding what the law actually gives you, before you sign, is some of the most valuable divorce advice there is.
Why the house usually belongs to both of you
California is a community property state. Under Family Code section 760, all property acquired by a married person during the marriage while domiciled in this state is community property. Section 2550 then tells the court to divide the community estate equally, except on the written agreement of the parties or on oral stipulation in open court.
In most cases that means the family home belongs to both spouses, even when only one name appears on the deed. That comes as a surprise in places like Irvine, where it is common for a single spouse to be on the loan because the lender wanted the stronger credit file at purchase. A loan is a financing document. It does not decide who owns the equity.
What a court will not split down the middle
Separate property generally stays with the spouse who owns it. Family Code section 770 covers property owned before marriage and anything received during the marriage by gift, bequest, devise, or descent. An inheritance from a parent sits squarely inside that definition.
A home can also be part separate and part community. A down payment made with money earned before the marriage traces back to a separate source, while the equity built by paying down the loan during the marriage belongs to the community.
Here is the part that catches people, and it is worth reading twice. Section 2640 reimburses that separate contribution, but it states the amount is reimbursed "without interest or adjustment for change in monetary values." A down payment of two hundred thousand dollars made in 2009 comes back as two hundred thousand dollars. It does not come back as the share of today's Newport Beach value that those dollars quietly turned into over sixteen years.
That one clause moves more money than almost anything else on the page.
The four ways the family home actually gets divided
| Path | How it works | What usually stops it |
|---|---|---|
| Sell the home | Both spouses agree to list it, sell it on the open market, and divide the equity. | One spouse is attached to the house and will not sign the listing agreement. |
| Buyout | One spouse buys the other's share of the equity and keeps the property. | The buying spouse cannot qualify for a new mortgage on their own. |
| Deferred sale | The court delays the sale and awards temporary exclusive use to the custodial parent of a minor child. | The resident parent cannot carry the payments and the upkeep. |
| Court decision | Where the spouses cannot agree, the judge divides the community estate. | Nothing stops it. This is what happens when the other three fail. |
Selling is usually the strongest financial outcome for both sides, and I would rather say that plainly than pretend the four options sit on equal footing. An open market sale produces a number the market agreed to, paid in cash, divided once. A buyout produces a number two people argued about, funded by debt one of them carries alone for the next thirty years.
The exception is real, though, and it has grown teeth since rates moved. When the existing loan carries a rate that cannot be replaced today, keeping the house can be worth more than the extra dollars an open sale would bring. Run that comparison on paper before anyone gets emotional about it.
The deferred sale order, which most people have never heard of
Family Code section 3800 defines a deferred sale of home order as an order that temporarily delays the sale and awards the temporary exclusive use and possession of the family home to a custodial parent of a minor child, in order to minimize the adverse impact of the dissolution on the welfare of that child.
It is not automatic. Under section 3801, the court first determines whether it is economically feasible to maintain the payments on any note secured by a deed of trust, the property taxes, the insurance, and the condition of the home comparable to that at the time of trial. It weighs the resident parent's income against those costs. Then it asks whether spousal support or child support is available, and whether any other source of funds could close the gap.
Spouses can also agree to wait on their own, without any court order at all. That version is far more common, and it carries a risk nobody enjoys discussing: two people who are no longer married still co-own a mortgaged asset together, and somebody has to pay for the roof when it goes.
The loan is what decides most buyouts
A buyout only works if the buying spouse can qualify for a new mortgage on their own income, at today's rates, without the other spouse's earnings on the application. This is where most buyout plans die, and they usually die about three weeks after both parties have already agreed on the number.
Get the pre-qualification first. An agreement built on a loan that never funds is worse than no agreement, because the months spent waiting for it are months the house was not on the market.
If what you need is the arithmetic itself, what comes off the top before anyone divides anything, I worked through it line by line in House Buyout in a California Divorce: How Much Do You Actually Owe Your Spouse?
A house in a divorce is not a normal listing
Two clients, two attorneys, one asset, and no room for an agent who takes sides. If a property is part of your dissolution, start with a conversation rather than a listing appointment.
Schedule a Free ConsultationWhy a neutral agent matters
The right agent works with both parties neutrally, stays inside the framework the attorneys have set, and keeps the focus on value rather than on who was wronged. That sounds obvious until you watch an agent who was hired by one spouse try to run an open house that the other spouse has every right to attend.
Neutrality is also where pricing stops being a formality. A Mission Viejo tract home with dozens of comparable sales behind it all but prices itself, and two appraisers will land close together. A custom property in the hills above Laguna Niguel, or an older estate in Newport Beach with no true comparable on the street, does not. That is exactly where two spouses end up holding two valuations that are nowhere near each other, each convinced the other hired the wrong appraiser.
My background is useful here in a way it rarely is elsewhere. I went to law school, I have handled divorce, probate and trust sales for twenty-three years, and I am used to being the only person at the table who is not arguing for one side. If you want the wider view of how these sales actually run, I covered it in Selling Your House During a Divorce in California.
Five things to do before you sign anything
- Get the house valued by someone who is not working for either side, and get the valuation in writing before any number is discussed.
- Ask the lender for a current payoff demand. The balance on your statement is not the figure that pays off the loan at closing.
- Have the buying spouse pre-qualified before the buyout number is agreed, never after it.
- Trace any separate property contribution now, while the bank statements and the escrow file still exist. Section 2640 puts the burden of tracing on the person claiming the money.
- Read the agreement for who carries the taxes, the insurance and the repairs between signing and the day the transfer records. That gap is usually longer than either party expects.
Talk with Paula before you decide
If a house is part of your divorce, interview me before you hire anyone, including me. Ask how I handle two clients who are not speaking to each other. Ask what I do when one side wants the property listed on Monday and the other wants it off the market entirely.
Book a free strategy call and we will go through where your house sits among the four paths above, and what each one would actually net you.
Frequently Asked Questions
Do I have to accept a buyout offer in a California divorce?
No. A buyout offer from your spouse is an offer, and nothing in California law obliges you to take it. You can decline it. You can counter it, or ask the court to order the home sold instead. What you cannot do is stop the division from happening at all, because the court divides the community estate one way or another.
Who decides who gets the house if we cannot agree?
The judge does. Family Code section 2550 directs the court to divide the community estate equally unless the spouses agree otherwise in writing or by oral stipulation in open court. Neither spouse can block the process by refusing to participate, so the practical question is whether you want to shape the outcome or have it handed to you.
Is my inheritance protected if I put it into the house?
An inheritance is separate property under Family Code section 770. If you traced it into the house, section 2640 reimburses the contribution to the acquisition of the property, but the statute says the amount is reimbursed without interest or adjustment for change in monetary values. You get the dollars back, not the appreciation those dollars earned.
Can we delay selling the house until the children finish school?
Sometimes. A deferred sale of home order temporarily delays the sale and gives exclusive use to the custodial parent of a minor child. Before granting one the court first determines whether it is economically feasible to maintain the loan payments, the property taxes, the insurance and the condition of the home. Spouses can also agree to wait without a court order, which is more common and carries its own risks.
Stay Connected
New posts on probate, trust, divorce and luxury sales in Orange County land every week. Subscribe to the blog, listen to the podcast on Spotify, or follow along on Instagram and YouTube.
Paula Aragone
Aragone & Associates
949-415-4784 | [email protected]
Paula Aragone, CA DRE #01364746
Aragone & Associates | First Team Real Estate, CA DRE #01008773
4 Corporate Plaza Suite 100, Newport Beach, CA 92660
We are real estate professionals, not attorneys or tax advisors. Nothing here is legal or tax advice, and the statutes cited are summarized rather than reproduced in full. Talk to your family law attorney about how any of this applies to your own dissolution.
Tags: divorce real estate, property division, house buyout, community property, deferred sale of home, Orange County divorce, selling a house in divorce, Newport Beach real estate
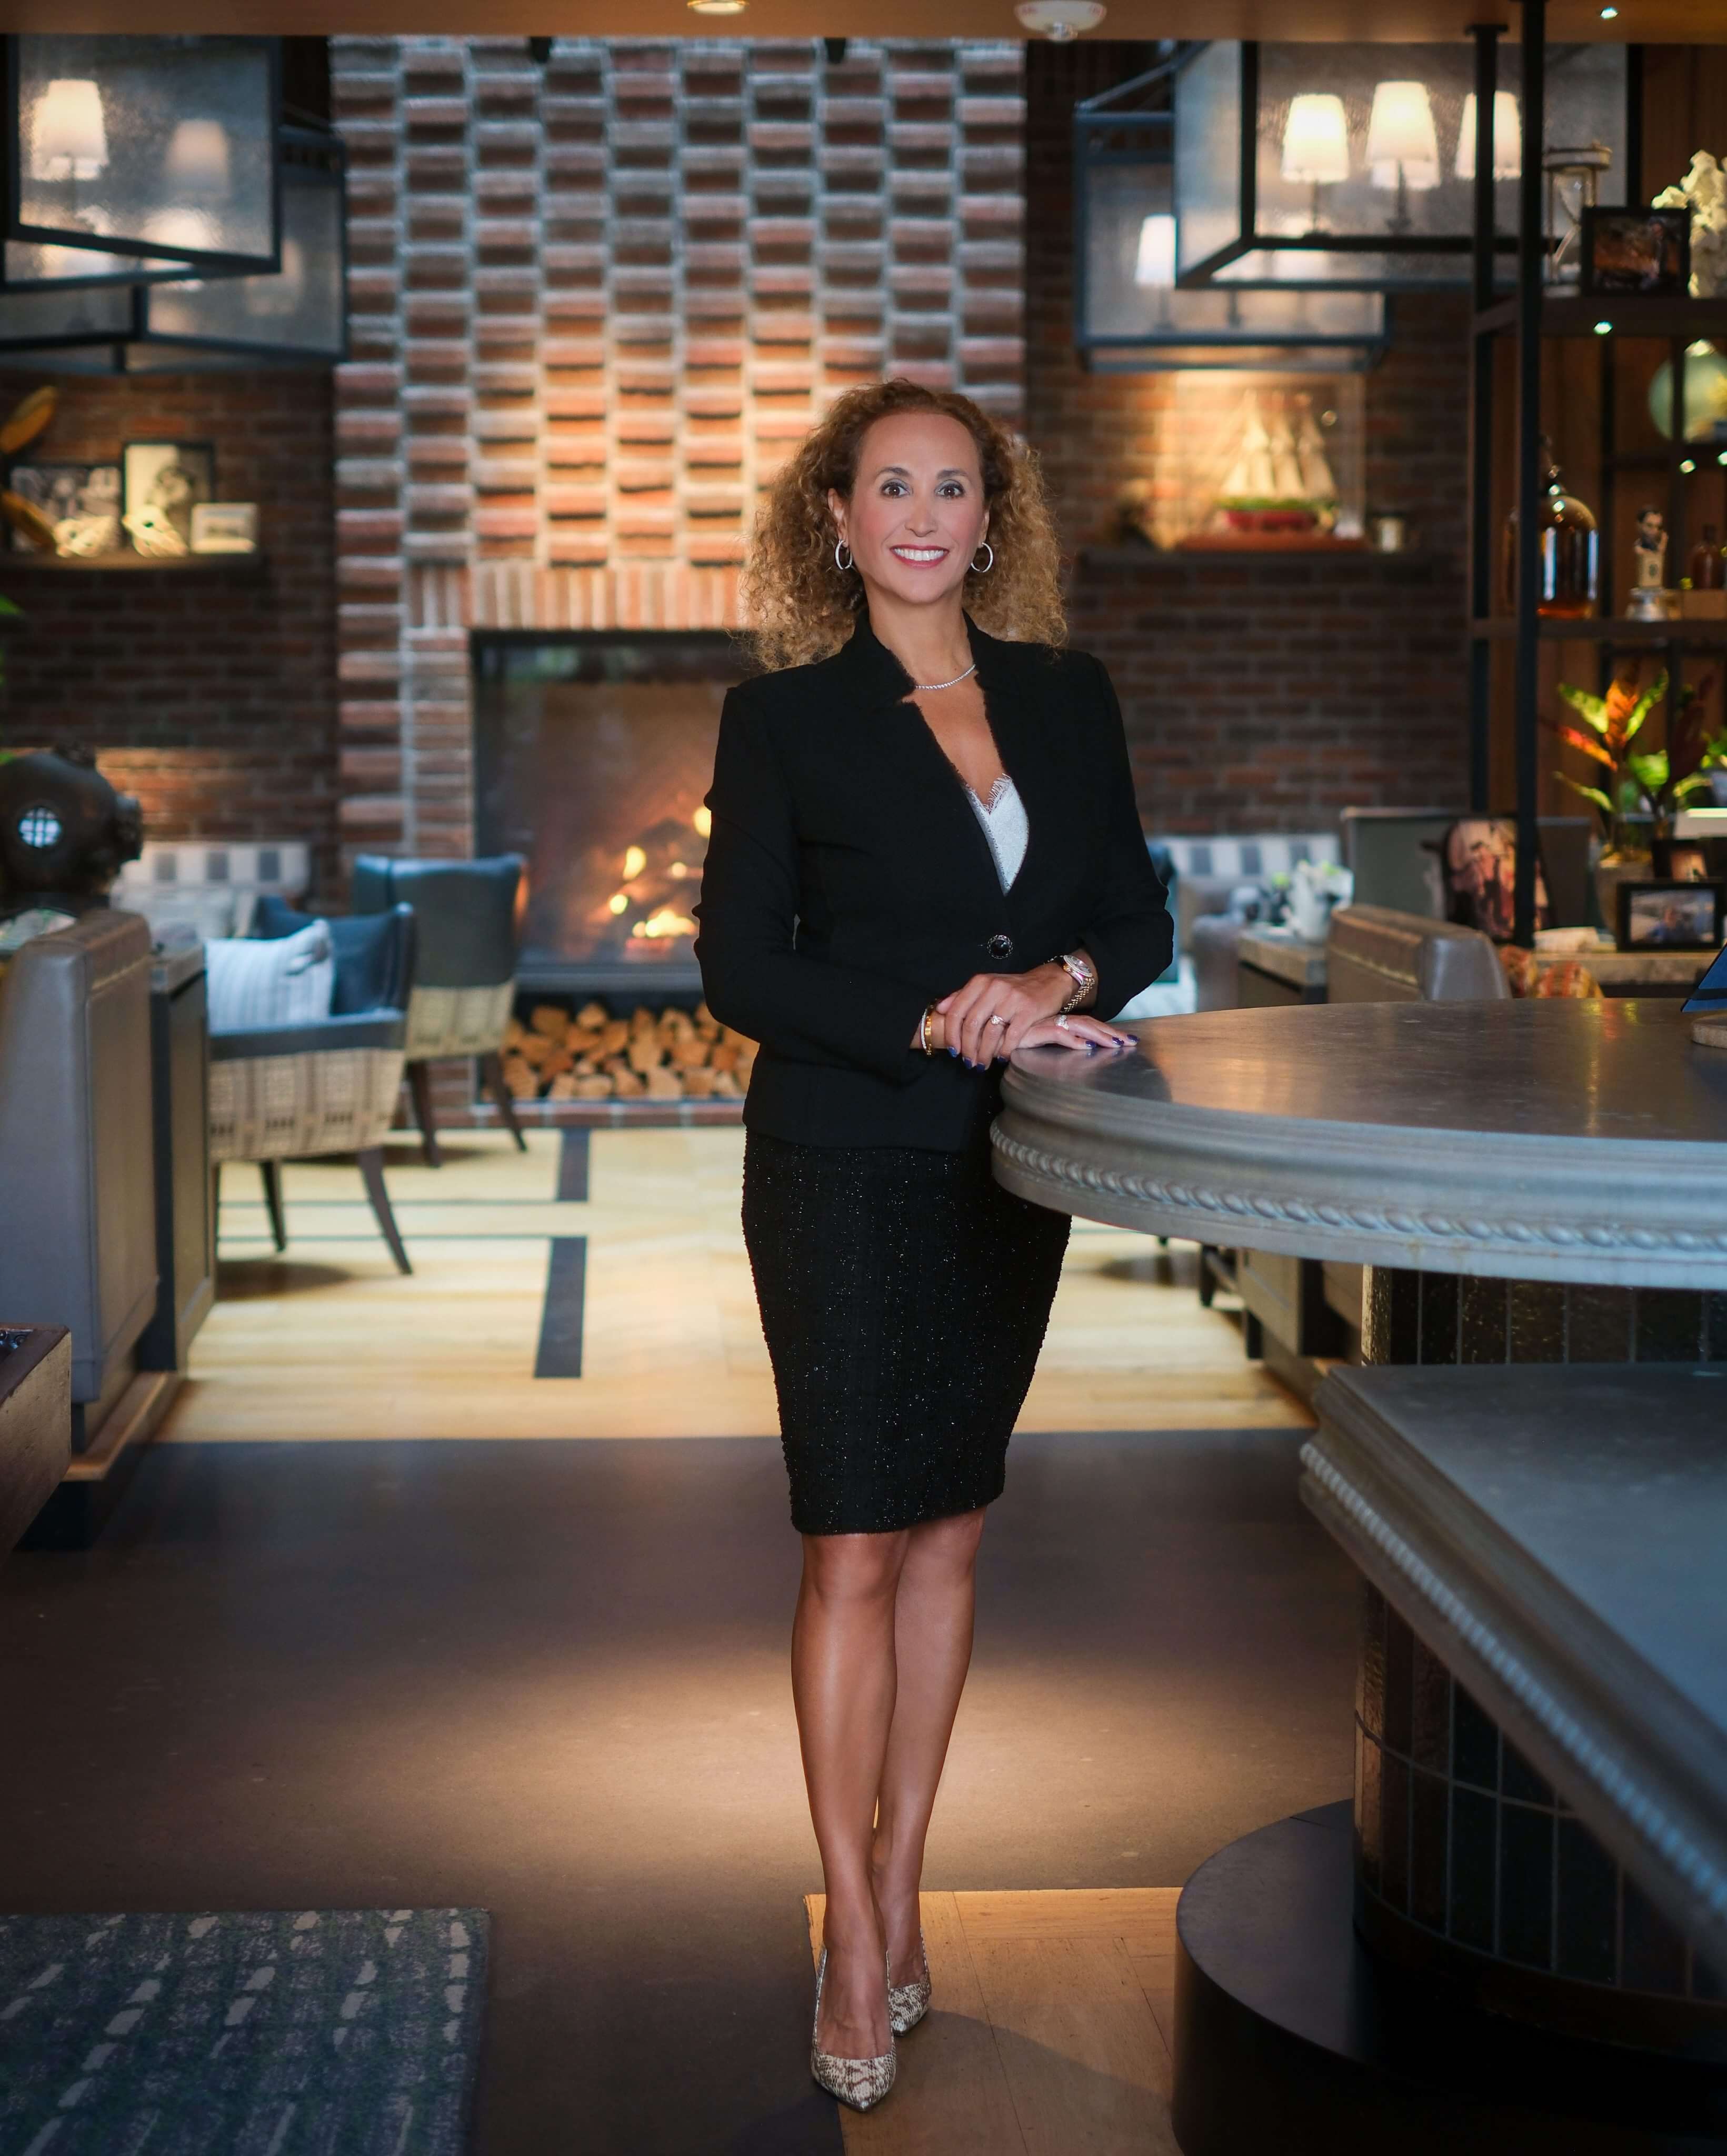
Paula Aragone
Paula has spent twenty-three years and more than 900 transactions on the parts of real estate that arrive with paperwork attached: probate, trust administration, divorce and senior downsizing across Orange County. She is a Certified Probate Real Estate Specialist and an SRES designee, holds a law school background she uses more often than she expected to, and works with attorneys and fiduciaries throughout the county.
Before you sign, find out what the house is really worth
One conversation is usually enough to tell you whether a buyout, a sale or a deferral is the better outcome for your side of the ledger.
Call (949) 415-4784Schedule a Consultation